


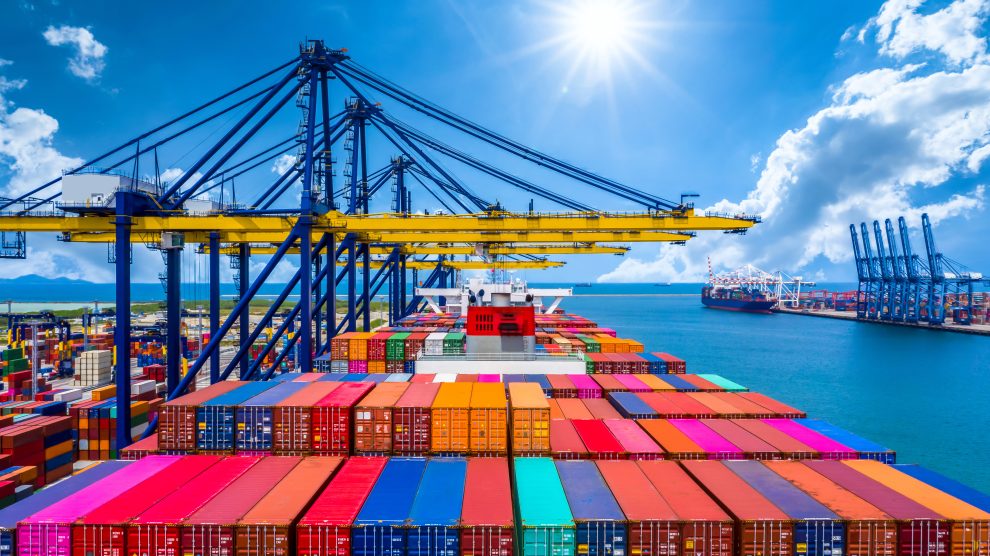
The GEP Global Supply Chain Volatility Index, a leading indicator tracking demand conditions, shortages, transportation costs, inventories and backlogs, based on a monthly survey of 27,000 businesses, showed that manufacturers accelerated precautionary stockpiling in October, reflecting growing concerns about future inflation and supply disruptions.
The increase was particularly pronounced in North America, where the safety stockpiling indicator more than doubled from September, and in Europe, where inventory building rebounded sharply.
This signals that manufacturers are purchasing additional materials to protect production against higher future costs and potential shortages, even as the pace of global purchasing growth moderates.
While this inventory buildup may support manufacturing activity in the near term, it also ties up working capital and creates a risk of weaker purchasing demand once companies have accumulated sufficient stock.
Meanwhile, global transportation costs increased for the second consecutive month, adding to already high inflationary pressures here.
Despite these concerns, global manufacturing activity remained resilient. Purchasing demand continued to grow, supported by sustained strength across Asia and improving European demand. However, overall global supply chain pressures eased in October as material and labor shortages declined.
“Manufacturers are increasingly concerned about what’s ahead, particularly inflation and the risk of renewed supply disruptions,” said John Piatek, vice president of consulting at GEP. “They’re responding by building larger inventory buffers to protect production and manage future costs. The concern is what happens next. This additional purchasing is supporting manufacturing activity today, but it also ties up working capital. Once inventories are built, purchasing could slow, creating a drag on manufacturing and the wider economy in 2027.”
October 2026 key findings include:
- Demand: Factory purchasing activity growth remained strong in October, in line with the general trend seen across most of the year to date. The U.S., China and Germany were key drivers of this expansion. Resilient demand for inputs also reflected concerted efforts by procurement managers to protect against further material price inflation and shortages.
- Inventories: Globally, reports of stockpiling due to price or supply concerns rose in October and were historically high. Safety stockpiling was the strongest in five months in North America, and European manufacturers also rapidly bolstered their inventory buffers.
- Material Shortages: Reports of supply shortages were historically high, registering above the long-run average for an eighth successive month, although they were the least pronounced since March, just after the outbreak of the Middle East conflict. Oil, electronic and electrical components were widely reported as being in short supply, as well as metals.
- Labor Shortages: Reports of manufacturers accumulating backlogs due to staff shortages were at their lowest since February 2025, indicating that labor was not a restrictive factor for capacity in October.
- Transportation: With global oil prices rising throughout October, the transportation cost index rose to a four-month high.


