The number of real estate technology startups has increased 300% over the past decade, seizing the opportunity to address the industry’s biggest challenges through technology, according to data released by JLL. The first half of 2021 saw US$9.7 billion of funding activity in the first half of 2021, the most active first half on record. Additionally, the market shows signs of maturation as funding begins to shift toward established players and increasing consolidation drives the emergence of industry leaders.
“While real estate technology adoption was on the rise before the COVID-19 pandemic, it has become essential for today’s leading real estate players, buildings and spaces,” said Ben Breslau, chief research officer at JLL. “Technology is at the center of the most important trends shaping business and real estate. That includes hybrid work, health and safety, and sustainability initiatives, all of which are in high demand. That’s why we expect funding within this sector to break records this year.”
Amid the Fourth Industrial Revolution, and accelerated by the COVID-19 pandemic, new technologies have proliferated to take advantage of developments in computing power, analysis and connectivity. The number of startups across the real estate industry has grown rapidly in the past decade — from under 2,000 to nearly 8,000 — as companies look to apply these new technologies. However, there has been a migration in funding and mergers and acquisitions (M&A) to more established industry leaders.
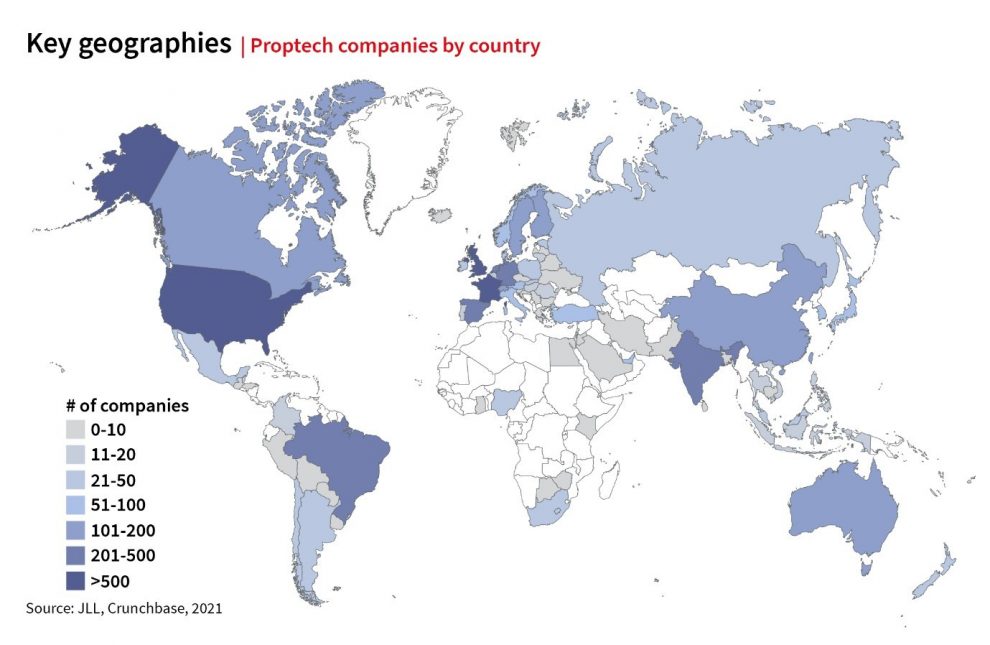
The nearly 8,000 companies, identified by JLL, that provide technology solutions in the built environment have collectively raised more than US$97 billion of equity funding in the past decade. Built environment technology startups can now be found in most countries around the world. In alignment with the wider tech ecosystem, the U.S. continues to account for the most company conceptions and fundraising — 50% of funded companies over the past decade. U.S. cities and regions hosting the greatest number of proptech startups include New York; San Francisco, Los Angeles and the Silicon Valley in California and Chicago, Illinois.
Although China has significantly fewer companies, it is the second largest market in terms of funding, with more than US$16 billion raised since 2010. India, Singapore and Australia have been the principal markets for fundraising outside China in Asia Pacific. Top cities include Bengaluru and Delhi in India; Singapore; Beijing, China and Sydney, Australia.
In Europe, the UK and Germany make up the majority of fundraising across the region, followed by France, Spain and Sweden. Top cities include London, U.K.; Paris, France; Barcelona, Spain; Berlin, German and Helsinki, Finland.